 blog
Common Mistakes First-Time Homebuyers Make
Table of Contents
- Why First-Time Homebuyers Make Costly Mistakes
- Mortgage Preapproval Mistakes That Sink Offers
- Skipping the First-Time Homebuyer Checklist
- Underestimating First-Time Homebuyer Closing Costs
- Using the Home Inspection Checklist for Buyers the Right Way
- Ignoring the Full Cost of Homeownership
- Rushing the Home Buying Process
- Conclusion: Slow Down and Get It Right
- Frequently Asked Questions
Last Updated: October 13, 2026
Why First-Time Homebuyers Make Costly Mistakes
Most buying mistakes are not caused by bad luck.
The common mistakes first-time homebuyers make usually fall into one of two buckets: money mistakes and timing mistakes. Money mistakes include underestimating closing costs and ignoring the full cost of ownership.
Here is the good news. Every one of these errors is avoidable with a little planning.
The Consumer Financial Protection Bureau's home loan toolkit lays out the paperwork and disclosures you will see at each stage.
Below, we break down each mistake, what it costs you, and how to sidestep it.
Mortgage Preapproval Mistakes That Sink Offers
A preapproval letter tells sellers you can actually borrow the money. Skipping it, or confusing it with prequalification, is one of the most damaging mortgage preapproval mistakes a buyer can make.
Confusing Prequalification With Preapproval
Prequalification is a quick estimate based on what you tell a lender. Preapproval is a verified review of your income, debts, and credit. Only preapproval carries weight with a seller.
A common mistake is touring homes with only a prequalification in hand. Sellers treat those offers as weaker, and you may lose the home to a buyer who did the real work first.
Opening New Credit or Changing Jobs Mid-Process
Your lender rechecks your file before closing. A new car loan, a new credit card, or a job change can undo your approval overnight.
- Do not finance furniture or a car before closing
- Do not change jobs without telling your lender
- Do not make large unexplained deposits
- Keep your credit cards open and paid down
Skipping the First-Time Homebuyer Checklist
A written first-time homebuyer checklist keeps you from missing steps in a long process. Without one, details slip through, and those details cost money.
Here is the short version we give our own clients:
- Check your credit report for errors
- Save for down payment and closing costs
- Get preapproved, not just prequalified
- Set a realistic budget with a monthly payment cap
- Tour homes and compare neighborhoods
Keep the list somewhere you will see it. Check items off as you go.
Underestimating First-Time Homebuyer Closing Costs
First-time homebuyer closing costs are the fees paid at the finish line, and they are the single most underestimated expense in the process. Buyers often budget for the down payment and forget everything else.
Closing costs typically cover lender fees, title work, appraisal, prepaid taxes, and insurance. They are separate from your down payment, and they are due in cash at closing.
What the Loan Estimate Actually Tells You
Your lender must send a Loan Estimate within three business days of your application. This form lists your projected rate, monthly payment, and every closing cost line by line.
Read it closely. Compare it to any revised version you receive later. If a number jumps, ask why in writing.
The CFPB guide to closing costs explains which fees can change and which are locked once you receive the estimate.
Using the Home Inspection Checklist for Buyers the Right Way
A home inspection checklist for buyers is not a pass-or-fail test. It is a repair list, and how you use it decides what you pay later.
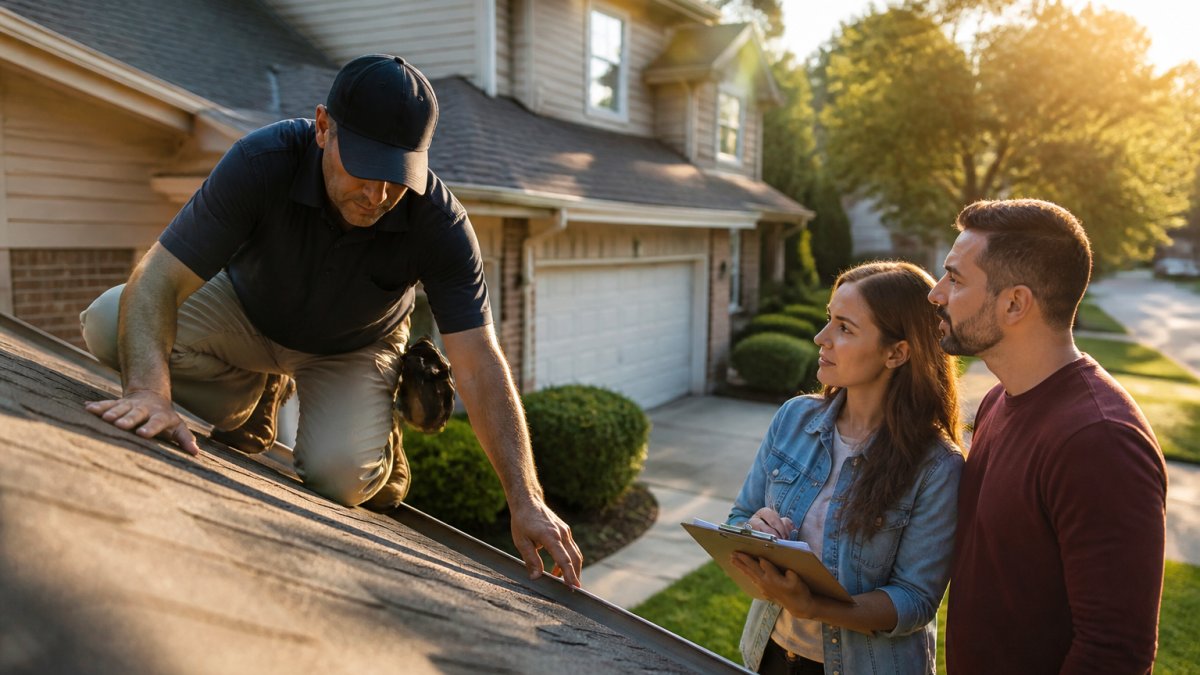
An inspection covers the systems that are expensive to fix: roof, drainage, HVAC, plumbing, electrical, foundation, and structural elements. The inspector writes up what is wrong, what is aging, and what needs a closer look from a specialist.
How to Prioritize the Inspection Report
Not every line item deserves a negotiation. Sort the findings into three tiers before you respond:
- Tier 1, Safety and structural. Foundation movement, active roof leaks, failed HVAC, electrical hazards, and sewer or septic problems. These are the items most likely to justify a repair request, a credit, or walking away.
- Tier 2, Major systems nearing end of life. A water heater or roof with a few years left is not a defect today, but it is a future cost. Ask for a credit or a home warranty rather than a full replacement.
- Tier 3, Maintenance and cosmetic. Loose outlet covers, caulking, and minor drainage issues are normal for a used home. Most sellers will not negotiate these, and asking for them can weaken your position on the items that matter.
Negotiating Repairs or Credits After the Inspection Report
Once you have the report, you have three options:
- Ask for repairs. The seller fixes the items before closing. This works best for safety items where you want the work documented and permitted.
- Ask for a credit. The seller reduces the price or pays toward your closing costs, and you handle the work. Credits are usually faster and give you control over the contractor, but your lender may cap how much seller credit you can receive.
- Walk away. If the findings are serious, your inspection contingency lets you exit and keep your earnest money, provided you respond within the contingency deadline in your contract.
Watch the Contingency Clock
Your inspection contingency has a deadline, and missing it can cost you your deposit and your leverage. A common pattern is a contingency window of seven to ten days from acceptance, though the exact number is negotiated in your contract.
If you need more time, ask for an extension in writing before the deadline passes. Do not assume a verbal agreement will hold.
Focus on the big-ticket items. Roof, foundation, and major systems are worth negotiating. A loose outlet cover is not.
Ignoring the Full Cost of Homeownership
Your monthly mortgage payment is not your monthly housing cost. The full cost of ownership adds several lines that renters never see, and the fastest way to avoid this mistake is to build a sample monthly budget before you tour a single home.
Start with the four components every lender escrows or expects you to pay:
| Cost | What It Covers | Paid How |
|---|---|---|
| Principal and interest | The loan itself | Monthly |
| Property taxes | Local tax on your home's assessed value | Monthly escrow or yearly |
| Homeowners insurance | Fire, storm, liability coverage | Monthly escrow or yearly |
| Private mortgage insurance | Required when your down payment is below the lender's threshold | Monthly, until you reach the equity level your lender requires |
Then add the lines renters never budget for:
- Utilities. Water, sewer, trash, gas, and electric are usually on you now. Ask the seller for the last twelve months of utility bills, many sellers will share them during the inspection period.
- Maintenance and repairs. A common planning rule is to set aside about 1% of the home's purchase price per year for upkeep. On a $300,000 home, that is roughly $3,000 a year, or $250 a month, and it does not include one-time replacements.
- Major systems reserves. Roofs, HVAC systems, and water heaters have finite lifespans. If the inspection shows an HVAC unit near the end of its service life, start a separate reserve now rather than waiting for the failure.
- HOA dues. If the home is in a community with a homeowners association, dues are a fixed monthly cost on top of your mortgage, and special assessments can appear with little warning. Review the HOA's budget and reserve study before you remove your contingency.
- Emergency fund. Keep three to six months of housing costs in reserve after closing. Buyers who drain their savings for the down payment are the ones most exposed when the first repair arrives.
A Sample Monthly Ownership Budget
Here is how the pieces fit together for a hypothetical $300,000 purchase with a 10% down payment and a 30-year fixed loan. The mortgage figure is illustrative only, your actual rate depends on your credit, lender, and the day you lock.
| Line item | Monthly estimate |
|---|---|
| Principal and interest | Varies with your rate and loan amount |
| Property taxes | Based on your county's assessed value and rate |
| Homeowners insurance | Based on coverage, deductible, and location |
| Private mortgage insurance | Required while your down payment is below the lender's threshold |
| Utilities | Ask the seller for twelve months of bills |
| Maintenance reserve (about 1% of price per year) | Roughly $250 on a $300,000 home |
| HOA dues, if applicable | Per the association's current schedule |
Fill in the first four lines with real numbers from your Loan Estimate and your insurance agent, then add the last three from the seller's disclosures and your own reserve target.
Buyers who plan only for the mortgage often feel house-poor within the first year. Buyers who build the full budget above usually do not.
Rushing the Home Buying Process
Speed feels good in a hot market. It also causes the worst mistakes on this list.
Buyers who rush skip the inspection, waive contingencies, and stretch their budget past comfort. Then they live with the result for years.
Here is the pace that works:
- Prepare your finances and credit first
- Get preapproved before you tour
- Tour enough homes to know the market
- Make an offer with sensible contingencies
- Complete the inspection and negotiate
- Confirm your loan estimate and lock your rate
- Close and do a final walk-through
The U.S. Department of Housing and Urban Development's buying guide covers the roles of agents, lenders, and inspectors so you know who handles what.
Conclusion: Slow Down and Get It Right
The mistakes on this list share one root cause: moving faster than the process allows. A first purchase rewards patience, and the buyers who take their time end up with fewer surprises and better terms.
That is where we come in. Martin Home Team brings 15 years of North Dallas real estate experience and a veteran-owned, detail-first approach to every transaction.
Frequently Asked Questions
What mistakes should first-time homebuyers avoid?
The most damaging mistakes first-time homebuyers make include getting prequalified instead of fully preapproved, draining savings to zero for the down payment, skipping the home inspection, and opening new credit accounts during the mortgage process. Each one either weakens your offer, leaves you without an emergency fund, or puts your loan approval at risk. A first-time homebuyer checklist that covers financing, budgeting, and inspection steps helps you catch these issues before they cost you.
Why should you avoid opening new credit accounts while buying a home?
Your mortgage lender pulls your credit report again before closing. A new credit card, car loan, or furniture financing adds to your debt-to-income ratio and can drop your credit score. Even a small change can push your ratio past the lender's threshold or move you into a higher mortgage rate tier. Wait until after closing to finance anything new, including appliances or furniture for the house.
What costs should first-time homebuyers plan for beyond the down payment?
First-time homebuyer closing costs typically cover lender origination fees, title search and insurance, appraisal, recording fees, and prepaid items like homeowners insurance and property taxes. Beyond closing, budget for moving expenses, utility deposits, immediate repairs, and a maintenance fund. Ask your mortgage lender for a Loan Estimate early so you can see the full picture before you commit to a purchase price.
How can first-time homebuyers avoid overpaying for a house?
Compare at least three mortgage lenders and request a Loan Estimate from each so you can compare rates and fees side by side. Get preapproved before house hunting so you know your realistic budget. Then look at recent comparable sales in the neighborhood, not just the list price. A buyer's agent who knows the local market can tell you whether a home is priced fairly or whether there is room to negotiate.